Getting hit from behind is one of those experiences that doesn’t fully land until after it’s over. The adrenaline fades, and you’re left with a damaged car, a sore neck, and questions about what comes next. Most people assume that because the other driver hit them, everything else will sort itself out. It usually doesn’t. Insurance companies have their own interests to protect, and knowing your rights before dealing with them makes a genuine difference in what you walk away with.
Whether your crash happened on a busy highway or a quiet side street, the legal framework for pursuing compensation follows similar principles across most states. Someone researching how to sue for a rear-end collision in St. Louis, for example, will find that the core questions—who was negligent, what damages resulted, and how liability gets proven—are the same ones that apply in most states.
Fault Isn’t Always as Simple as It Looks
There is a common assumption among people that whoever rear-ends someone is automatically at fault. That is true in most cases, but not always. A driver who stops suddenly without reason, cuts off another vehicle, or has broken brake lights can share some fault.
How that affects your claim depends on the state you are in. Some follow a pure comparative fault system where you can recover even if you were mostly at fault. Others bar recovery if you’re more than 50% responsible. Knowing where your state stands matters before you start negotiating.
What You Are Actually Entitled to Claim
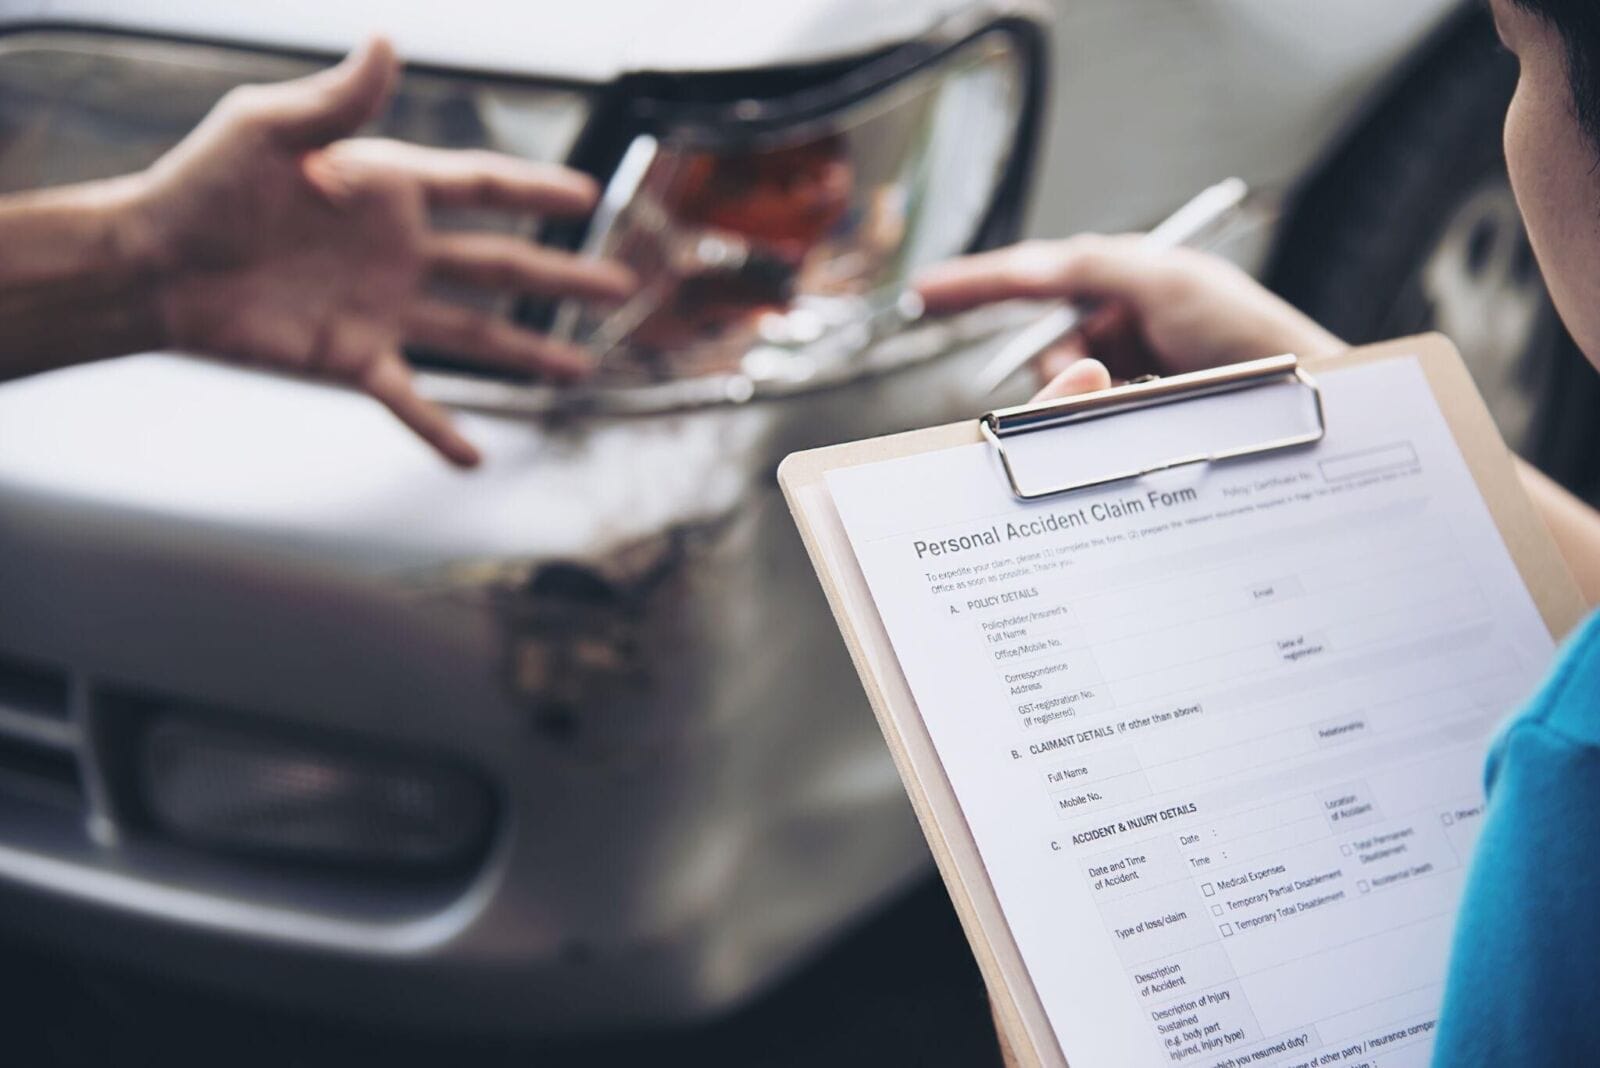
The damages available after a rear-end collision go beyond the obvious. Most people know they can claim vehicle repair costs and medical bills. Fewer people actually realize the full scope includes lost wages, loss of future earning capacity, pain and suffering, and emotional distress.
Soft-tissue injuries like whiplash are routinely undervalued by adjusters because they don’t always appear on imaging. Documenting every symptom, every doctor’s visit, and every way the injury has affected your daily life builds the record needed to support a full claim.
Don’t Let the Insurance Company Set the Terms
Needless to say, the other driver’s insurance company is not on your side. Their adjuster’s job is to settle your claim for as little as possible, and they’re experienced at it. A fast settlement offer shortly after the crash is a reason for caution, not relief—it almost always arrives before the full picture of your injuries is clear.
Once you accept, you typically sign away the right to any further compensation, even if symptoms worsen. You’re also under no obligation to give a recorded statement. Doing so without legal advice often creates statements used to limit what you recover.
Evidence Collected at the Scene Carries More Weight Than People Expect
Photos from the scene, witness contact information, and the police report are foundational to any rear-end collision claim. The damage pattern on both vehicles can help reconstruct what happened and at what speed.
Dashcam footage, when it exists, is often decisive. If nearby traffic or business cameras may have captured the crash, an attorney can send a preservation letter before that footage gets deleted. Evidence gathered in the immediate aftermath often determines how credible your account is when it matters most.
Timing Matters More Than Most People Realize
Every state sets a deadline for filing a personal injury lawsuit, and rear-end collision claims are no exception. Missing the statute of limitations means losing the right to sue entirely, regardless of how strong the case is.
These deadlines range from one to six years depending on the state, and the clock typically starts on the accident date. Getting legal advice early—well before any deadline looms—also gives your attorney time to build a proper case rather than rushing under pressure.
You Have More Leverage Than the Insurance Company Wants You to Know
Rear-end collisions look simple on the surface, but the claims process is built in ways that consistently favor the insurer over an unrepresented claimant. Understanding your rights—what you can claim, how fault works, and what the insurer is actually doing—shifts that balance. Most personal injury attorneys offer free consultations, so there’s no cost to finding out exactly where you stand before deciding how to proceed.