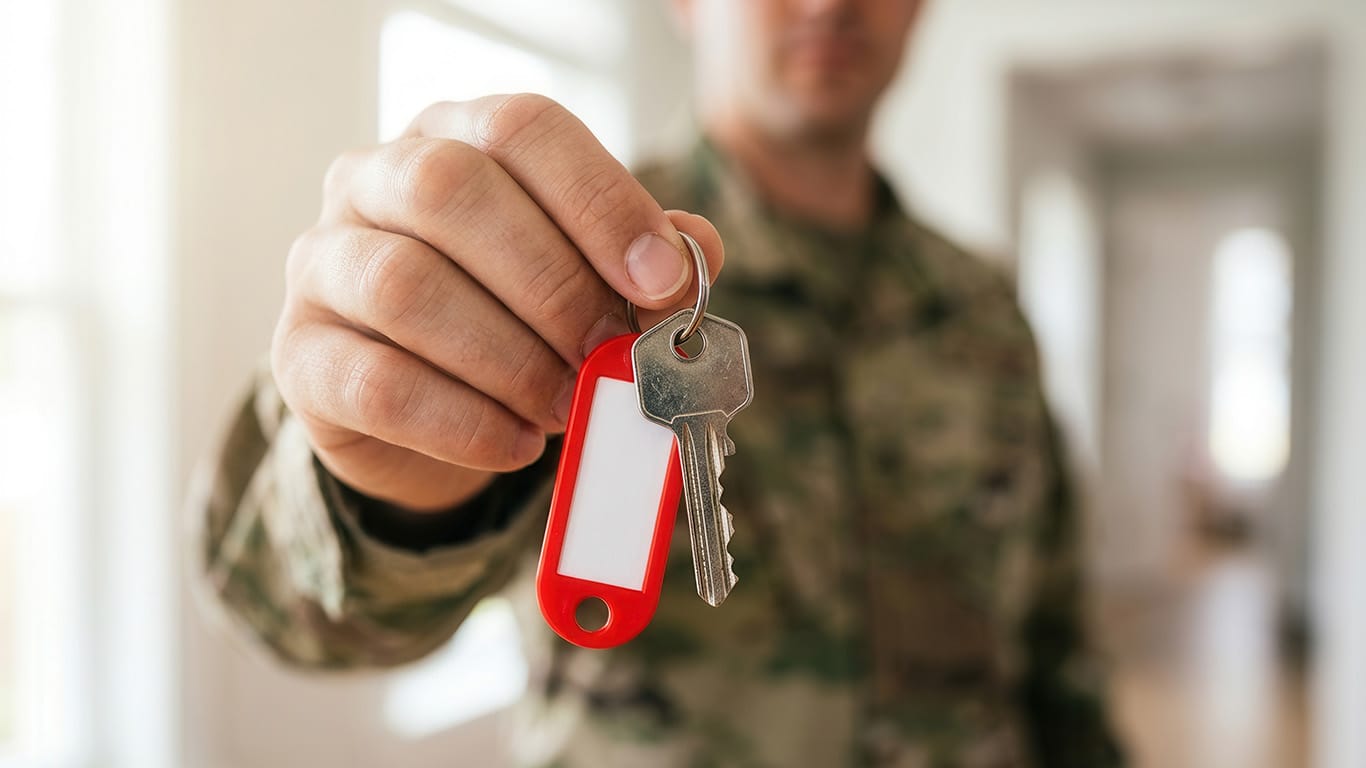
After 21 years in the U.S. Army, I appreciate hearing “Thank you for your service.” As a Realtor, I also believe there is a practical way to put that appreciation to work: helping veterans understand their housing options before they make a major move.
Military families often make those decisions around circumstances a listing description cannot capture. Orders can create a tight timeline. A spouse may need to find work in a new city. Retirement may offer the first opportunity in years to choose a community without another assignment on the horizon.
In Surprise and the surrounding West Valley, those decisions can mean finding a home within a workable commute of Luke Air Force Base or moving closer to family in retirement. The planning should begin with the people making the move and the benefits available to them.
MORE NEWS: Honeywell is building new $500 million manufacturing facility in Tempe
DEEPER DIVE: 10 Arizona restaurants make Yelp’s Top 100 Mexican food spots
Revisit the benefit before ruling out a move
A previous VA-financed purchase does not necessarily mean a veteran has exhausted the benefit. Under VA’s eligibility rules, entitlement may be restored after a home is sold and the prior VA loan is paid in full. In some circumstances, remaining entitlement can support another purchase while an existing VA loan is still outstanding.
Start with a Certificate of Eligibility and have a lender experienced with VA financing review prior use, available entitlement, and any down payment requirement. Credit, income, and occupancy requirements still apply. That review belongs early in the process, before a veteran assumes the next purchase is out of reach.
Understand the cash needed to buy
VA-backed purchase loans can allow eligible borrowers to buy without a down payment and do not require monthly mortgage insurance. Those features can help preserve savings for moving expenses or emergencies. Lender approval, sufficient entitlement, and appraisal requirements still matter.
Closing costs and prepaid expenses can still be due. Ask for a written estimate of the cash needed, including any funding fee, and identify what negotiated seller or builder credits would cover.
Check funding-fee exemption status, too. Veterans receiving VA compensation for a service-connected disability are among those exempt. For perspective, on a hypothetical first-use $400,000 VA purchase loan with no down payment, a 2.15% funding fee would equal $8,600. An eligible exemption removes that fee. Confirming status before closing can make a meaningful difference.
Choose a home for the life ahead
For a service member relocating near Luke, I would start with the actual commute at the hours they expect to travel, the move-in date, and the household budget during the transition. A home that looks convenient on a map deserves a closer look before someone commits from another state.
For a veteran planning retirement, the questions may be different. Will the home remain manageable? Are there steps between the garage and living area? How accessible is the primary bathroom? How far away are family, medical appointments, and the activities that make a community feel familiar?
A single-story floor plan or recreation center may be appealing, but each buyer should consider how the home will work over time. In active-adult communities, verify occupancy rules and recurring fees before deciding the neighborhood fits.
Leave room for inspection and planning
A VA appraisal addresses value and minimum property requirements. It does not replace an independent home inspection, which VA strongly recommends. Buyers still need an opportunity to investigate the home’s condition and understand potential repairs.
That matters when distance or military timing puts pressure on a purchase. Video tours can help narrow the choices, but they cannot answer every question about a property. Coordinate the lender’s timeline, inspections, closing, and possession before scheduling the moving truck. Discuss a backup plan if the transaction takes longer than expected.
Consider VA assumable homes when planning a move
Veteran homeowners should review the next purchase before committing to the sale of their current home. The plan should account for expected proceeds, temporary housing if needed, and what financing will be available afterward.
A VA loan assumption may create another option for buyers and sellers. With approval, the buyer takes over the existing mortgage balance and its remaining terms. An existing fixed rate below the buyer’s new-loan alternatives could make the home appealing, but the upfront funds and approval process deserve equal attention.
For example, a hypothetical $425,000 purchase with a $325,000 remaining loan balance leaves a $100,000 gap before closing costs. The buyer must cover that difference; discuss any proposed additional financing with the servicer. An assumption can require substantial upfront funds even when the existing loan originally required no down payment.
If a buyer proposes assuming an existing VA loan, involve the loan servicer early. Release from liability and restoration of entitlement are different matters. An assumption without a substitution of entitlement can leave the seller’s entitlement tied to the loan. Ask how the proposed arrangement would affect the next purchase before agreeing to it.
My guide to VA Assumable Homes in Surprise and the West Valley explains these considerations and provides a search of homes reporting existing VA financing. Those listings are a starting point. Seller participation, loan details, and assumption approval must be confirmed for each property.
Five questions to ask before the next move
- What VA entitlement is available to me, and what financing can I qualify for?
- What cash will I need at closing, and what savings should I keep afterward?
- Does this home support my household’s needs over the next several years?
- How will the sale, purchase, and moving dates work together?
- Which decisions need confirmation from my lender, loan servicer, or VA?
This Veterans Day, I hope more veterans take time to revisit their housing benefits, even if a move is still months away. A clear understanding of the options can give a family time to prepare, adjust the budget, or decide to stay where they are. Veterans deserve that opportunity to make the next move on their own terms.
Author: Todd Pooler is a Realtor with Realty ONE Group, serving Surprise and Arizona’s West Valley. A Surprise resident since 2006 and licensed since 2013, he is a retired U.S. Army Senior Noncommissioned Officer with 21 years of service and holds the Military Relocation Professional designation. His work includes military relocation and VA homebuyers.